§ 0 — The question
What needs
to be true?
Every great outcome, whether a sale, an acquisition, or a raise, begins as a list of things that aren't true yet. We work through that list with technology companies and the funds behind them. Then we get the deal done.
§ 1 — What we do
Before a company reaches the next milestone, a few things have to be true.
Here's where we usually start.
Long before a deal
Most of the work happens here, months or years before anyone calls it a process.
- 01
The story is true.
Buyers understand why you win, not just what you sell.
- 02
The right people already know you.
A buyer who has watched you for a year pays differently than one who met you in a data room.
- 03
The portfolio makes sense.
Every asset fits the thesis, or it has found a better home.
- 04
The next acquisition makes you more valuable, not just bigger.
Buy-side work that starts from the outcome, not the target list.
- 05
The capital is right.
The right partner, the right amount, at the right moment.
At the table
The deal closes.
Senior-led from the first call to the wire.
- Every trick, seen before. Negotiation led by a senior banker who has watched buyers re-trade, slow-walk, and suddenly “discover” issues in diligence.
- Always ready to go back out. Materials stay current through the whole process, so if a buyer stumbles, you’re back in market in weeks, not months.
- Buyers held to their word. Timelines and terms tracked in writing. Slippage gets called out the day it happens.
§ 2 — Who we are
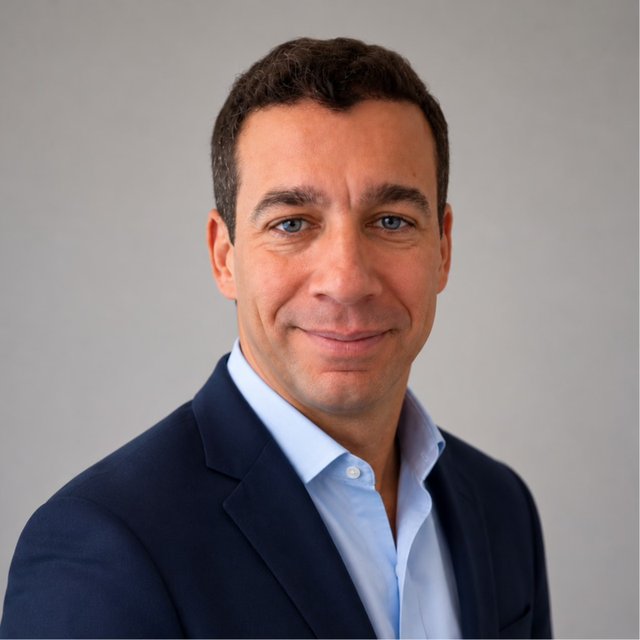
Josh Moses, Founder & Managing Partner
JSM Strategies was founded in Chicago by Josh Moses, after twenty years as an investment banker to technology companies.
Before founding JSM, Josh was a Managing Director at Intrepid Investment Bankers and, before that, at Vaquero Capital, advising software and tech-enabled services companies and their investors on sales, acquisitions, and growth investments. His deepest work is in supply chain and logistics software, healthcare IT, and vertical software.
Josh is as likely to reference what his daughter calls "boring books" as the 1993 Chicago Bulls. A history student by training and an omnivorous reader, he is a devoted fox and weirdo in a world of zipper-fleece hedgehogs.
He believes narratives are the key to a successful process, that we standardize at our peril, and that things are connected in ways that aren't immediately obvious.
He's spent two decades telling the stories of founders and investors while trying not to pretend to be anything he doesn't want to become.²
MBA, Kellogg School of Management · AB, University of Chicago
² “We are what we pretend to be, so we must be careful about what we pretend to be.” —Kurt Vonnegut, Mother Night
§ 3 — What we're looking for
Four situations where we do our best work.
Sell-side, buy-side, capital raises, and combinations, for software and tech-enabled services companies, their founders, and the funds behind them.
-
i.
Lightly capitalized companies in complex situations.
For founders who want to get to the next level. We align early, invest our time (and occasionally our capital), and build a narrative around what the ultimate exit looks like.
-
ii.
Sponsor-backed businesses that haven't hit plan, or no longer fit it.
Still interesting companies whose thesis, for one reason or another, hasn't gone according to plan, or that have outgrown the strategy around them. We align with you on what a good outcome looks like, and make sure it gets the time and attention it requires.
-
iii.
Buy-side assignments that fill gaps.
We work out where you should be spending time, identify white space that creates new narrative potential, and relentlessly pursue targets, through the negotiation.
-
iv.
Combinations.
We identify companies of similar size that have a better value proposition together than apart. Then we play matchmaker.
Where we've spent twenty years
Supply chain and logistics software. Healthcare IT. Vertical software.
Where we're looking
What changes in an AI-first world, where software gets cheaper to build and data and services become the differentiators.
Size and scope
We meet companies early, often below $3 million in revenue, and stay with them through transactions many times that size.
Muscle memory
We've seen hundreds of companies across dozens of verticals, so we usually know what a buyer will ask before they ask it.
§ 4 — A constraint we chose
We can't be everywhere at once.
So we don't try. We take on a handful of assignments at a time, and we pick companies we'd gladly bet our time on. Not every opportunity is a fit, and that's the point.
§ 5 — Transactions
Proof the list gets finished.
Selected transactions from prior firms.¹
¹ Tombstones only. The stories behind them are better told in person.
§ 6 — Notes
Thinking out loud about what needs to be true.
Essays on markets, companies, technology and the occasional battle cat. Also on LinkedIn.
In the queue
- We don’t make He-Men
- Dental patient engagement and disco
- When AI commoditizes the feature, what's left to sell?
- Economists, $20 bills, and innovation
§ 7 — Start a conversation
Our goal is for you to make a ton of money.³ We find it's better to just say so.
Tell us a little about where you are and where you want to end up. We read every note, and we reply to the ones that look like a fit.
³ Most of what we earn, we earn when you do. It focuses the mind.